
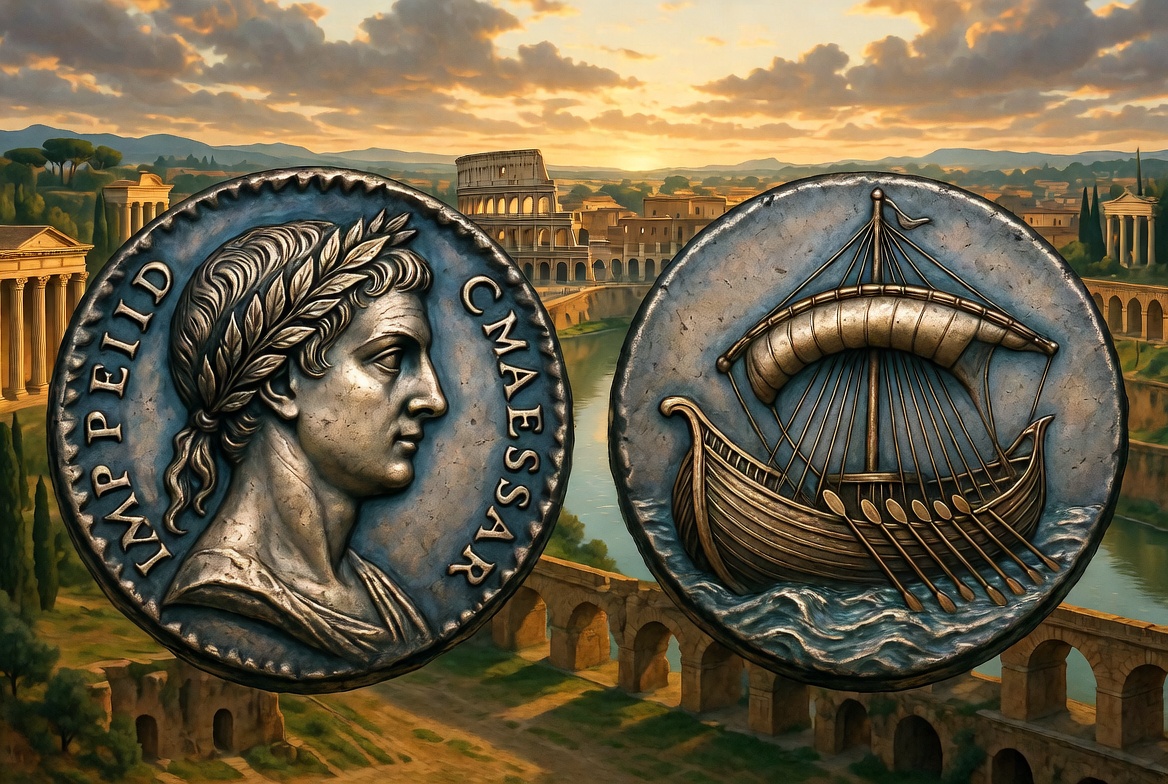
There have been moments in history when the flip of a coin changed everything. In 1969, the Chicago Bears lost a coin toss to the Pittsburgh Steelers for the first overall draft pick. The Steelers took Terry Bradshaw, who went on to win four Super Bowls and land in the Hall of Fame. Coin flips have been part of organized sports for decades, but their roots go back much further. The earliest known example comes from ancient Rome, where people flipped coins engraved with a ship on one side and the emperor’s head on the other. They called it navia aut caput — ship or head. Medieval England used a similar ritual with a cross and a pile to settle disputes fairly.
For centuries, flipping a coin has served as humanity’s way of letting pure chance decide — the ultimate neutral arbiter.
Today, President Trump is essentially flipping his own coin after nominating Kevin Warsh as the new Chair of the Federal Reserve. His first choice, Jerome Powell, drew sharp criticism for not cutting interest rates aggressively enough. Frustrated, Trump turned to Warsh to take the helm of the nation’s financial clearinghouse. Bond investors worldwide are now watching Mr. Warsh’s first few months closely. Warsh has a clear vision for reshaping the Fed’s enormous balance sheet — but the structural forces at play may limit how much real difference that vision can make.
I know most people don’t spend their days thinking about central-bank ledgers. But the size and makeup of the Fed’s balance sheet quietly influence everything from mortgage rates and Treasury yields to the overall stability of the financial system. Let’s walk through the latest thinking in plain English and what it might mean for everyday investors like you.
First, What Exactly Is the Fed’s Balance Sheet?
The Fed acts as the giant financial clearinghouse for the U.S. economy. Its “balance sheet” is simply a ledger showing what it owns (mostly U.S. Treasuries and mortgage-backed securities) and what it owes (bank reserves, currency in circulation, and the Treasury’s general cash account).
Through years of quantitative easing during crises like 2008 and 2020, the Fed grew this portfolio to a peak of about $8.5 trillion in 2022. It has since trimmed it down to roughly $6.4 trillion. That’s still enormous by historical standards. Those holdings keep the banking system flush with reserves, which in turn supports lending, liquidity, and generally lower interest rates.
Why Warsh Wants to Shrink and “Cleanse” It
Kevin Warsh has long argued that a balance sheet this large pulls the Fed away from its core job—keeping inflation around 2% and supporting maximum employment. When the Fed owns so many securities, it starts directing money toward specific parts of the economy (think housing via mortgage bonds). That blurs the line between monetary policy (the Fed’s domain) and fiscal policy (Congress and the Treasury’s domain). It can also make the Fed look less independent — a concern shared by both political parties.
Warsh’s vision is straightforward: make the balance sheet smaller overall and more neutral in its makeup. The goal isn’t to create chaos — it’s to refocus the Fed and reduce its direct footprint in the markets.
The Real Challenge: You Can’t Just Sell Everything Overnight
Here’s where it gets tricky. The Fed already tried aggressive balance-sheet reduction (known as quantitative tightening, or QT). When reserves dropped too low, money-market rates became volatile and liquidity felt “tight.” The central bank had to pause and even step back in with some asset purchases to stabilize things.
Liquidity is now back to “ample” levels, but any further shrinkage has to be handled carefully. The banking system, the Treasury, and everyday cash usage all create steady demand for Fed liabilities. Without adjustments elsewhere, the balance sheet tends to expand “organically” just to keep the system running smoothly.
So How Could Warsh Actually Make Progress?
There are three realistic paths forward that wouldn’t require slamming the brakes on the economy:
1. Easing certain bank regulations After the 2008 crisis (and again in 2023), rules pushed banks to hold extra high-quality liquid assets, including big reserves at the Fed. Carefully relaxing some of those requirements — while keeping banks safe — could lower overall reserve demand. This option probably has the biggest potential impact, though it faces some debate inside the Fed.
2. Changing how the Fed supplies liquidity Instead of holding trillions in bonds, the Fed could lend reserves directly to banks (and possibly others) through on-demand facilities — similar to how the European Central Bank operated for years. Banks would manage reserves more efficiently, and the Fed could gradually reduce its securities holdings without starving the system of liquidity.
3. Revaluing the Treasury’s gold holdings This one is a bit wild to think about. Here’s why: the government still carries its gold on the books at the old 1973 price of about $42 per ounce. At today’s market prices (around $4,500/oz), revaluing it could create roughly $1.2 trillion in accounting gains. The Treasury could use that to cut future borrowing needs, and the Fed could adjust its portfolio in an orderly way — potentially shedding some securities without market drama. It’s a creative, politically appealing idea (for Trump) that could deliver a cleaner balance sheet with minimal disruption.
The Bottom Line
Whatever the new Fed Chair’s personal intentions, the structural forces at play are simply too strong to resist. Organic balance sheet expansion, relentless political pressure against meaningful sterilization, and the growing temptation of gold revaluation — an option few in the White House will want to block — all point in the same direction.
The inflationary trajectory remains firmly intact. The Fed’s balance sheet may shift in composition, but its ultimate effect on purchasing power will not.
Navia aut caput.
Heads: inflation.
Tails: inflation.
