
Long-term financial security doesn’t happen by chance. A well-designed financial plan is key to a long, healthy financial life. We are adept at seeing the big picture of your finances and then addressing the details that make the plan work – including those that are often overlooked. Clients have 5 main control areas in their life that we review in detail: spending, saving, timing, risk, and legacy.
By Christopher Krzus, CFP® / Wolfstone Wealth
Spending. Saving. Timing. Risk. Legacy. Most plans miss at least one
A financial plan for an executive or high-income professional is more than a spreadsheet and a savings rate. It’s a set of connected decisions across spending, saving, timing, risk, and legacy – and the pieces that get missed are often the ones that matter most later.
I’m a fee-only fiduciary CFP® working with executives and high-income professionals in the Chicago suburbs and virtually across the country. My focus is seeing the full picture and addressing the details that many plans overlook.
Not sure what a financial plan actually covers, or whether you need one?
The first conversation is a 20-minute call; no paperwork, no commitment. Just a conversation to see if it makes sense to work together.
The Financial Planning Questions We Hear Most Often
Most clients who come to us for financial planning aren’t in crisis. They’re making good money. They’re saving something. They just have a persistent feeling that the pieces aren’t adding up the way they should. These are the six conversations we have most often.
I’m making great money. So why don’t I feel more secure?
This is because income and security are different things. Income is what comes in. Security is what stays – what survives a market drop, a job change, a health event, or a tax bill you didn’t see coming. High earners are often the most exposed in this gap, because their lifestyle, their tax burden, and their investment decisions all scale up together without a plan holding them in proportion. This is where a good financial plan can tie both income and security together.
I’m too busy to manage this properly, but I don’t want to be ignored either.
This is a common tension for high earners. They want a plan that doesn’t require constant attention, yet they also don’t want to hand everything over and disappear from the process.
A well-built financial plan sits in the middle of those two extremes. It handles the day-to-day details and ongoing coordination, so you don’t have to manage it yourself, while still bringing you in when a real decision needs to be made. You’re involved when it matters — not buried in the parts that don’t.
What if the market drops right when I’m ready to retire?
This is one of the most legitimate fears in financial planning, and one of the most neglected in retirement planning. The sequence of your investment returns matters enormously in the decade before and after retirement — a bad year early can permanently reduce what your portfolio can sustain. Planning for this isn’t about predicting markets. It’s about structuring the portfolio and the income strategy, so a bad year doesn’t become a permanent problem. Learn more about this in our Sequence of Returns Risk in Retirement post.
College costs and retirement are hitting at the same time. How do I handle both?
This is a timing problem, and timing is one of the five areas we plan explicitly. The mistake most people make is treating college savings and retirement savings as separate decisions. They’re not — they compete for the same dollars at the same time, and the sequencing of which gets funded first, and how, has real long-term consequences. We model both together.
I worry I’ll outlive my money.
That’s a planning problem, not a math problem. The math is straightforward; project the assets, project the expenses, test against different market scenarios. What makes it feel unsolvable is that most people have never actually run the numbers in a way that accounts for their specific situation. Once you have a real plan, the fear usually shrinks considerably. It doesn’t disappear — but it becomes a thing you’re managing, not a thing managing you.
I manage my own money through Schwab. Why do I need a financial planner?
Managing investments is only one part of financial planning. The rest – tax strategy, retirement income sequencing, estate coordination, insurance, and cash-flow structure -is where things often drift out of alignment when no one is connecting them.
Most self-directed investors handle the investment piece reasonably well. What tends to create the gaps is the lack of coordination across the rest of the plan. That’s the part a fiduciary financial planner is specifically there to handle.
Does one of these sound like a conversation you’ve been putting off?
Schedule a 20-minute call at WolfstoneWeath or call 630-640-3582
How we Approach Financial Planning
Financial planning for executives and high-income professionals works best when five areas are treated as a connected system rather than separate conversations: spending, saving, timing, risk, and legacy. At Wolfstone Wealth, we build the plan around all five, with particular attention to the pieces that often get missed when the focus stays too narrow on investments alone.
Integrated Plan Design
We put investment strategy, tax planning, estate structure, and cash flow into one coordinated picture. The plan is built around your actual income, timelines, and goals — not a generic template.
Retirement Timing and Income Sequencing
We look carefully at when and how you plan to draw income, including the risk that a weak market early in retirement can permanently change what’s sustainable. The goal is a plan that can absorb a difficult stretch without forcing major changes later.
Tax Coordination
Tax strategy is built into the plan from the start, not added at the end. This includes Roth conversion opportunities, RSU vesting timing, withdrawal sequencing, and other decisions that can reduce the total tax burden over time rather than just optimizing a single year.
Risk Planning Across All Five Areas
Risk is broader than portfolio volatility. It also includes gaps in insurance, outdated estate documents, and cash-flow structures that wouldn’t hold up if income were disrupted. We review exposure across all five control areas, not just the investments
Legacy and Estate Integration
Legacy planning is treated as a core part of the financial plan rather than a separate conversation for later. This includes beneficiary designations, estate tax exposure, preparing heirs, and making sure the financial plan and legal documents work together.
Fiduciary, Fee-Only Structure
As a fee-only fiduciary CFP®, I am compensated only by clients – no commissions, no product sales, and no referral arrangements. Recommendations are made because they fit your situation, not because they generate revenue for the firm. That structural difference matters.
Financial Planning Planning FAQs
These are the questions we hear most often from executives and high-income professionals evaluating whether to work with a financial planner. If yours isn’t here, the first conversation is a good place to start.
What does a fiduciary financial advisor actually do differently?
A fiduciary is legally required to put the client’s interests first — not the firm’s and not a product provider’s. A fee-only fiduciary also earns no commissions, so recommendations are made because they fit the client’s situation rather than because they generate revenue. In practice, this usually shows up as more integrated planning across investments, taxes, estate, and insurance instead of advice shaped by what pays the advisor.
What is a fiduciary financial advisor and how do I know if mine is one?
A fiduciary is legally obligated to put your interests ahead of their own and to disclose conflicts of interest. You can confirm this by asking directly, reviewing the advisor’s Form ADV (available through the SEC’s IAPD database), or looking for CFP® certification, which requires a fiduciary commitment. Many brokers and sales-based advisors operate under a lower “suitability” standard instead.
How much does a fee-only financial planner cost, and is it worth it?
Fee-only planners typically charge a flat annual retainer, an hourly rate, or a percentage of assets under management, with no commissions on top. Whether the cost makes sense depends on the complexity of your situation. For high-income professionals dealing with tax exposure, equity compensation, retirement timing, and estate planning at the same time, the value of coordination often outweighs the fee. At Wolfstone Wealth, the first conversation is a free 20-minute call to help determine whether that’s true for you.
What are the five control areas of financial planning?
The five areas clients can meaningfully influence are spending, saving, timing, risk, and legacy. A comprehensive plan treats these as connected pieces rather than separate decisions.
When should I start working with a financial planner?
The highest-value window is usually during the accumulation years – when income is strong, tax decisions still have leverage, and there is time to change outcomes rather than simply manage them. Waiting until retirement often limits options around Roth conversions, tax strategy, and estate planning. Many clients who later say they wish they had started earlier began in their late 40s or early 50s.
Do you work with clients outside the Chicago suburbs?
Yes. Wolfstone Wealth works with executives and high-income professionals virtually across the country, with in-person meetings available for clients in Naperville, Wheaton, and the greater Chicago area. Most of the work happens by video and secure document sharing, so location is rarely a barrier.
Still weighing whether this is the right fit?
The first call is always 20 minutes. No commitment, no paperwork. Schedule a call here, or call 630-640-3582 now.
About Christopher Krzus, CFP®
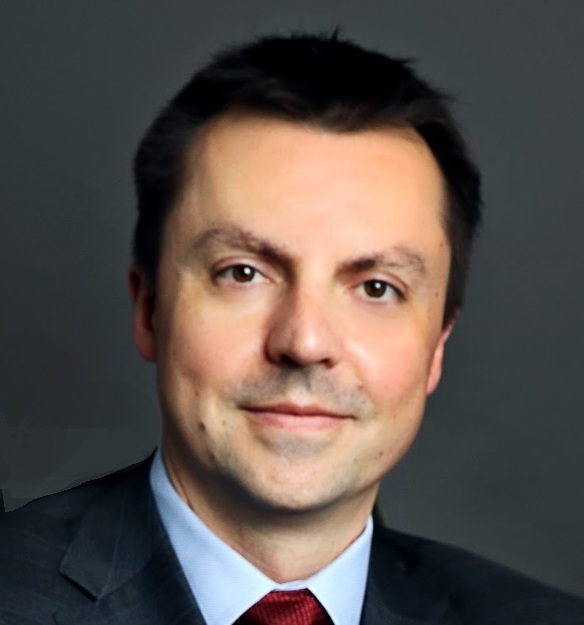
Chris Krzus is the founder and president of Wolfstone Wealth and a fee-only CERTIFIED FINANCIAL PLANNER® with more than two decades of experience. He began his career on the Chicago Board of Trade — an education in markets, risk, and the difference between conviction and noise that informs how he thinks about money to this day. He has since specialized in comprehensive financial planning and investment management for busy and successful tech and business professionals, executives in the accumulation phase, and people navigating major life transitions.
Chris works as a fiduciary, which means he is legally and ethically obligated to act in your interest at all times — not his firm’s, not a product provider’s. He earns no commissions. There are no proprietary products. Just a plan that works for you.
On the tax side specifically, Chris brings integrated thinking to the problems that fall between a tax preparer’s scope and a standard investment advisor’s: RSU and equity compensation planning, Roth conversion strategy, inheritance tax planning for growing estates, and withdrawal sequencing for clients approaching retirement. He coordinates with your existing CPA or tax professional where relevant, so nothing falls through the cracks between the people who are supposed to have it covered.
Not Sure Where to Start?
Most financial planning questions don’t have a clean answer until someone looks at the full picture. The right strategy depends on your income structure, your timeline, your tax situation, and a handful of other things that take about 20 minutes to understand.
Schedule a 20-minute introductory call →
No paperwork. No pitch. I work with a select number of clients. If it is a fit for both of us, we will know.