
Fee-Only CFP® Serving the Chicago Suburbs and Nationwide

By Christopher Krzus, CFP® / Wolfstone Wealth
Creating an estate plan is straightforward on paper. The real work—and the part that actually protects your family—is making sure it’s current, fully aligned with your financial reality, and understood by the people who will one day carry it forward. A will in a drawer doesn’t safeguard anyone. What matters is whether your plan reflects how you built the wealth and equips the next generation to preserve it.
At Wolfstone Wealth, we treat estate planning as an integrated financial conversation, not a one-time legal checkbox. We help high-income professionals, executives, and business owners in the Chicago area (and virtually across the country) maximize their legacy while preparing heirs to handle it responsibly.
Questions About Your Situation?
The first conversation is a 20-minute call — no paperwork, no commitment. Just a conversation to see if it makes sense to work together.
The Estate Planning Questions We Hear Most Often
Clients rarely come to us with a blank slate. They usually have documents in place—but they lack confidence that everything will function as intended when it matters most. These are the conversations we have again and again with people in their late 30s through mid-50s:
I trust my kids. I just don’t trust what money does to people.
That instinct is spot on. Sudden wealth without preparation has quietly unraveled more family legacies than market crashes ever have. We don’t withhold—we structure thoughtful, gradual transfers and help you have the real conversations now, while you’re here to guide them.
How do I make sure what I built actually lasts?
Most plans transfer assets. Few transfer the wisdom to manage them. We make heir education a core part of the process, because a legacy preserved across generations requires both money and the capacity to steward it.
I worry I’ll leave my family a mess with no plan.
This one hits hard. It’s less about the dollars and more about the burden you’d place on loved ones during their grief. A coordinated, up-to-date plan lifts that weight. It doesn’t have to be overly complex—it just has to be done right.
I’m a business owner. What happens to the business if something happens to me?
Business owner plans are uniquely vulnerable. The company grows, kids mature, and yesterday’s documents no longer match today’s reality. We integrate business valuation, buy-sell agreements, key person insurance, and succession planning into one living strategy.
My accounts and my will say different things about who gets what. Which one wins?
Beneficiary designations win—every time. That old 401(k) from your thirties overrides your will. We perform a full beneficiary and titling audit across every account and policy to eliminate these costly mismatches.
How do I protect what I’ve built from unnecessary taxes?
The federal estate tax exemption currently stands at $15 million per person for 2026 (indexed for inflation and made more permanent under recent legislation). Even so, strategic gifting, trust structures, and proper coordination remain powerful tools—especially for business owners where company value represents a large portion of the estate.
One of these resonate? That’s exactly where we start.
Schedule a no obligation 20-minute call, fill our our contact form or call 630-640-3582
Our Approach to High Net Worth Estate Planning
Estate planning for executives and business owners isn’t generic advice. It demands coordination across tax strategy, asset titling, family dynamics, and business realities. Here’s how we approach it:
Legacy and Heir Preparation
We design trust distributions, gifting timelines, and provisions around heir readiness—and we facilitate the financial conversations that turn inherited wealth into generational strength rather than erosion.
Inheritance Tax and Exemption Strategy:
We model your current and projected estate against today’s $15 million federal exemption threshold. Where it makes sense, we layer gifting programs, trust vehicles, and coordinated transfers to minimize exposure efficiently.
Estate Planning for Business Owners:
Valuation, buy-sell structures, key person coverage, and succession planning are woven directly into your overall estate plan—not handled in silos by disconnected advisors.
Beneficiary and Titling Audit:
A systematic review of retirement accounts, life insurance, TOD designations, and more to ensure everything aligns with your current wishes.
Irrevocable Life Insurance Trust (ILIT) Coordination:
When appropriate, we work with your estate attorney to keep life insurance proceeds outside the taxable estate, providing liquidity without inflating your tax bill.
Integrated Estate and Tax Coordination:
We collaborate closely with your existing estate attorney and CPA so the legal documents, account structures, investment strategy, and tax plan all pull in the same direction.
More Estate Planning FAQs
What estate planning does a business owner with young children actually need?
A current will, succession plan, key person insurance positioned outside the estate, trusts matched to heir maturity, and regular beneficiary reviews. Life moves fast—your documents need to keep up.
What is inheritance tax planning and who needs it?
It involves structuring gifts, trusts, and asset transfers to reduce the tax burden on heirs. It’s especially relevant for estates nearing or exceeding the federal exemption or for business owners whose company value is significant. Even with the current $15M exemption, proactive steps preserve more for your family.
Do beneficiary designations override a will?
Yes – on retirement accounts, life insurance, and similar assets. This is one of the most frequent (and expensive) oversights we catch. We have more on the specifics in Beneficiary Designations: Why This Small Detail Can Override Your Entire Estate Plan.
How do you, as a financial advisor, work with an estate attorney?
The attorney drafts the legal documents. We ensure those documents are properly funded, aligned with your full financial picture, and coordinated with tax and investment strategy. The two roles complement each other; coordination is where real value is created.
When should I start (or review) estate planning?
Before you “need” it. The most effective strategies take time to implement, and life events move faster than we expect. Regular reviews keep everything current.
Do you work with clients outside the Chicago suburbs?
Yes. Wolfstone Wealth works with executives and high-income professionals virtually across the country, with in-person meetings available for clients in Naperville, Wheaton, and the greater Chicago area. Most of the work happens by video and secure document sharing, so location is rarely a barrier.
About Christopher Krzus, CFP®
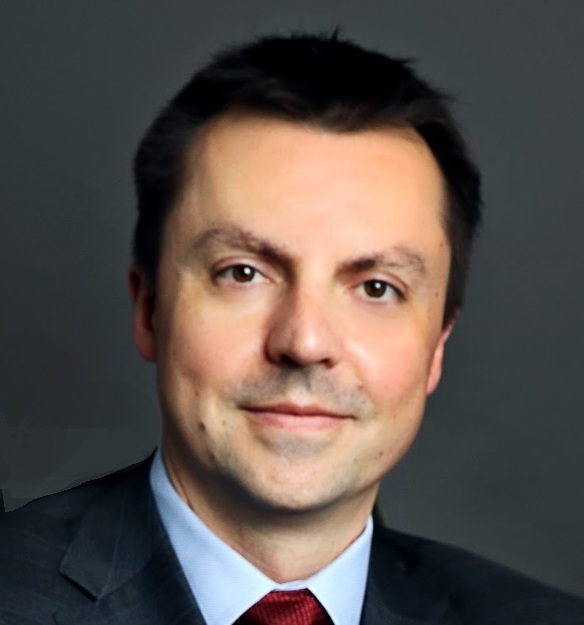
Chris Krzus is the founder and president of Wolfstone Wealth and a fee-only CERTIFIED FINANCIAL PLANNER® with more than two decades of experience. He began his career on the Chicago Board of Trade — an education in markets, risk, and the difference between conviction and noise that informs how he thinks about money to this day. He has since specialized in comprehensive financial planning and investment management for busy and successful tech and business professionals, executives in the accumulation phase, and people navigating major life transitions.
Chris works as a fiduciary, which means he is legally and ethically obligated to act in your interest at all times — not his firm’s, not a product provider’s. He earns no commissions. There are no proprietary products. Just a plan that works for you.
On the tax side specifically, Chris brings integrated thinking to the problems that fall between a tax preparer’s scope and a standard investment advisor’s: RSU and equity compensation planning, Roth conversion strategy, inheritance tax planning for growing estates, and withdrawal sequencing for clients approaching retirement. He coordinates with your existing CPA or tax professional where relevant, so nothing falls through the cracks between the people who are supposed to have it covered.
Not Sure Where to Start?
Estate questions rarely have simple, one-size-fits-all answers. The right path depends on your estate size, asset structure, family situation, and goals. Understanding that usually takes about 20 minutes.
Schedule a 20-minute introductory call →
No paperwork. No pitch. Just a conversation about where you stand and whether it makes sense to work together


