

By Christopher Krzus, CFP® / Wolfstone Wealth
Often overlooked by advisors, taxes are the not-so-hidden drain on your portfolio. And we know that taxes are a certainty for every client. Our discussion will be tailored into tax strategies specific for you and where applicable, we’ll consult with your tax professional to coordinate strategies.
For a broader rundown, see our guide to tax strategies for high-income earners
Your accountant reduces the damage.
Good tax planning is there before the damage happens.
For executives and high-income professionals, taxes are rarely a once-a-year event:
- RSU vesting schedules,
- Stock option exercises,
- Roth conversion windows, and
- Inheritance planning decisions
all interact in complex ways — and the cost of leaving them uncoordinated can be significant.
Most high earners already have a good accountant. What they often lack is a fiduciary partner who looks forward, models how these moving parts affect each other, and helps make decisions while there is still time to act. That is the gap we fill.
We work alongside your CPA or tax professional to coordinate strategies across your full financial life — investments, cash flow, equity compensation, and estate planning — so nothing falls between the cracks.
Questions About Your Situation?
The first conversation is a 20-minute call — no paperwork, no commitment. Just a conversation to see if it makes sense to work together.
My company withholds at 22% on my RSUs, but I’m in the 37% bracket. Am I going to owe a lot at tax time?
Yes — you will almost certainly owe additional tax. The IRS requires employers to withhold at the federal supplemental rate of 22%, regardless of your actual tax bracket. If your total income puts you in the 37% bracket (plus Illinois state tax), that creates a meaningful gap. The solution is proactive modeling before vesting so you can adjust estimated payments, coordinate with other income, or adjust withholding elsewhere in your compensation package. For the mechanics driving this — cliff vs. graded vesting, and why timing matters — see Understanding RSU Vesting Schedules.)
When my RSUs vest, should I sell right away or hold them?
It depends on more than taxes. We look at your overall concentration risk, time horizon, existing exposure to the same company, and whether holding creates a larger future tax event. Many executives instinctively hold, only to face bigger diversification and tax problems later. We help you build a systematic, multi-year selling approach that manages both risk and tax consequences before the shares hit your account.
My RSU pushed me over the Roth contribution limit this year. What are my options?
High vesting years create several issues at once. You may lose the ability to make direct Roth IRA contributions, you may trigger the 3.8% Net Investment Income Tax, and backdoor Roth conversions become more complex due to the pro rata rule. We coordinate your RSU vesting calendar with Roth conversion timing and other tax planning moves, so you avoid paying more tax than necessary.
My accountant files my taxes every year, but I don’t feel like anything is being planned.
This is the most common frustration we hear. Accountants are essential for compliance. Planning, however, is forward-looking. A good tax preparer looks backward at what happened. We look forward at what’s coming and help you change the outcome while you still can. When appropriate, we work directly with your CPA to coordinate strategies across investments, cash flow, and equity compensation — we’re not replacing them, we’re filling the gap between compliance and proactive planning.
We have a family estate, and I’m worried about inheritance tax planning — where do we even start?
The best strategies are only available when you plan early. For high-income professionals with growing assets, we focus on titling, beneficiary designations, gifting strategies, and trust structures while you’re still in the accumulation phase. We also help you think through the relational side — how to educate heirs so what you’ve built actually lasts across generations. This is not a one-time conversation; it evolves as your assets and family situation change. (This is core to our Estate Planning work — see that page for how we approach exemption strategy, trusts, and business succession in more depth.)
I’m approaching retirement and I’m not sure whether to keep converting to Roth or take income from traditional accounts first.
This is one of the most consequential decisions in the decade before and after retirement. The wrong sequence can create unnecessary taxable income, push you into higher Medicare premiums (IRMAA), and reduce the longevity of your portfolio. We model different withdrawal and conversion strategies against your full financial picture — tax brackets, Social Security, RMDs, and healthcare costs — to find the approach that fits your specific situation.
My income spiked this year. Will this affect my Medicare premiums in retirement?
It can. High-income years can trigger IRMAA (Income-Related Monthly Adjustment Amount) surcharges on your Medicare Part B and Part D premiums two years later. Because IRMAA is based on a two-year lookback, a single large RSU vesting year can create higher premiums for multiple years. We help you model the impact and identify planning opportunities to manage or minimize the long-term effect.
My RSU income this year was very high. Will I owe the extra 3.8% Net Investment Income Tax?
You may. The 3.8% NIIT applies to net investment income once your modified adjusted gross income exceeds certain thresholds. Large RSU vesting years can push you over those thresholds even if you don’t have significant investment income otherwise. We model your full-year income early and identify strategies (such as timing other income or deductions) to manage or reduce exposure. Learn more about RSUs
Recognize one of these? That’s usually where we start.
Schedule a 20-minute call or fill out the form to contact us | 630-640-3582
How We Approach Executive Tax Planning
We treat tax planning as a year-round, integrated discipline — not an annual compliance exercise. For executives and high-income professionals, we focus on anticipating income spikes, coordinating moving parts across your full financial life, and making decisions while there is still time to act.
RSU Tax Gap Modeling
Before each vesting date, we run precise projections so you know exactly what’s owed and can adjust estimated payments or withholding in advance, eliminating the common 15%+ under-withholding gap.
Equity Compensation Diversification Architecture
We design multi-year selling schedules for vested shares that balance concentration risk, capital gains timing, and tax bracket management — rather than leaving you with an all-or-nothing decision at vesting.
High-Income Roth & NIIT Coordination
We align RSU vesting years with backdoor Roth conversion windows and other planning moves to minimize or avoid the 3.8% Net Investment Income Tax and preserve long-term tax flexibility.
Multi-Generational Wealth Structuring
We implement early strategies around titling, beneficiary designations, gifting, and trust frameworks so your growing estate is positioned to minimize unnecessary state and federal transfer taxes — and so your heirs are prepared to steward what you’ve built.
Retirement Income & Medicare Premium Modeling
We map tax-efficient withdrawal sequences across traditional, Roth, and taxable accounts to manage lifetime tax brackets, avoid artificial income spikes, and reduce the risk of higher Medicare premiums (IRMAA) in retirement.
Tax Planning FAQs
These are the questions we hear most often from executives and high-income professionals with equity compensation and complex financial lives. If yours isn’t here, the first conversation is a good place to start.
How do RSUs get taxed when they vest — and what should I do before vesting?
Restricted stock units are taxed as ordinary income at vesting, based on the fair market value of the shares on the vesting date. Because the standard withholding rate (usually 22%) is often lower than your actual tax rate, planning before vesting is critical. Depending on your situation, this can include adjusting estimated tax payments, timing other income or deductions, or coordinating with Roth conversion planning. Learn more about Understanding RSU Vesting Schedules here.
What is the pro rata rule and how do I avoid it with a backdoor Roth?
If you have any pre-tax money in traditional IRAs, the pro rata rule treats all your IRA funds as one blended pool. This can turn a backdoor Roth conversion into a partially taxable event. Common solutions include rolling pre-tax IRA funds into a current employer’s 401(k) before converting, or using a mega backdoor Roth strategy inside a 401(k) if your plan allows it. The right approach depends on your plan rules and overall IRA situation.
How much does working with a fee-only CFP on tax planning actually cost?
At Wolfstone Wealth, we are compensated solely by our clients on a fee-only basis. Tax planning is included as part of our comprehensive financial planning service rather than billed separately. The first conversation is a 20-minute call with no obligation and no paperwork. We’ll discuss your situation and whether it makes sense to work together.
My RSU income pushed me over the threshold this year. Will I owe the 3.8% Net Investment Income Tax?
You may. The 3.8% NIIT applies to net investment income once your modified adjusted gross income exceeds certain thresholds. Large RSU vesting years can trigger this tax even if you don’t have significant investment income otherwise. We model your full-year income early and identify strategies to manage or reduce exposure where possible. Learn more about our High-Income Roth & NIIT Coordination work here.
What does a fiduciary financial advisor actually do differently on taxes?
A fiduciary is legally obligated to act in your best interest. On the tax side, that means recommending strategies because they’re genuinely right for you — not because they generate a commission or preserve a product relationship. It also means coordinating your tax picture across investments, cash flow, equity compensation, and estate planning. Many advisors refer tax questions to an accountant and leave the coordination to you. We fill that gap.
What is the pro rata rule and how do I avoid it with a backdoor Roth?
If you have any pre-tax money in traditional IRAs, the pro rata rule treats all your IRA funds as one blended pool. This can turn a backdoor Roth conversion into a partially taxable event. Common solutions include rolling pre-tax IRA funds into a current employer’s 401(k) before converting, or using a mega backdoor Roth strategy inside a 401(k) if your plan allows it. The right approach depends on your plan rules and overall IRA situation.
About Christopher Krzus, CFP®
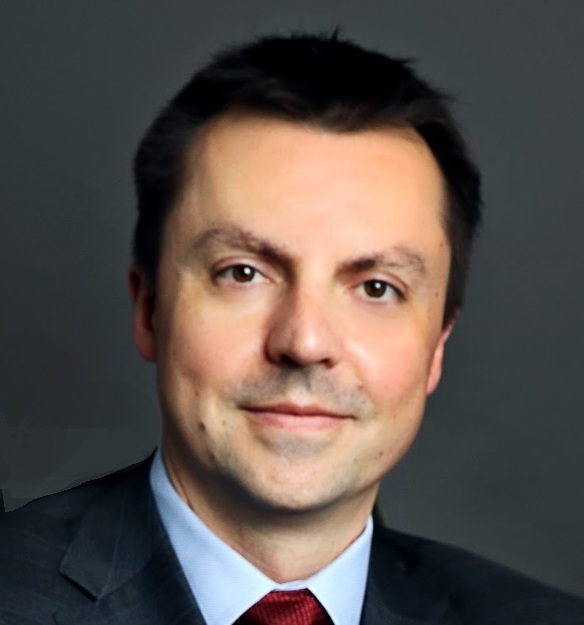
Chris Krzus is the founder and president of Wolfstone Wealth and a fee-only CERTIFIED FINANCIAL PLANNER® with more than two decades of experience. He began his career on the Chicago Board of Trade — an education in markets, risk, and the difference between conviction and noise that informs how he thinks about money to this day. He has since specialized in comprehensive financial planning and investment management for busy and successful tech and business professionals, executives in the accumulation phase, and people navigating major life transitions.
Chris works as a fiduciary, which means he is legally and ethically obligated to act in your interest at all times — not his firm’s, not a product provider’s. He earns no commissions. There are no proprietary products. Just a plan that works for you.
On the tax side specifically, Chris brings integrated thinking to the problems that fall between a tax preparer’s scope and a standard investment advisor’s: RSU and equity compensation planning, Roth conversion strategy, inheritance tax planning for growing estates, and withdrawal sequencing for clients approaching retirement. He coordinates with your existing CPA or tax professional where relevant, so nothing falls through the cracks between the people who are supposed to have it covered.
Not Sure Where to Start?
That’s exactly what the first conversation is for. Tax questions rarely have clean answers in isolation — the right strategy depends on your income, your equity comp schedule, your retirement timeline, and a handful of other things that take about 20 minutes to understand.
Schedule a 20-minute introductory call →
No paperwork. No pitch. We’ll talk about where you are and whether it makes sense to work together.


