
Insurance is easy to ignore until you need it. By then, the options are usually worse. The useful work happens earlier: look at what you already have, understand what it actually covers, and decide whether the gaps matter. That review is part of planning. It is not a product pitch.
By Christopher Krzus, CFP® / Wolfstone Wealth
What coverage do you actually have — and what is it for?
Most people I meet are not looking to buy more insurance. They either have coverage they have not reviewed in years, coverage only through work, or no real sense of why certain policies exist in the first place.
The first job is simple. We review the policies and benefits you already have, compare them with your income, family, assets, and estate documents, and show you where the gaps are. From there, implementation usually goes to a specialist. If you want help getting the coverage in place, that can be done through an independent agency.
I’m a fiduciary CFP® working with executives and high-income professionals in the Chicago suburbs and virtually across the country. I work with a select number of clients. The first conversation is a 20–30 minute Zoom call. No paperwork. No obligation.
Not sure whether your coverage still matches your life?
That is a good reason to look at it now, while the options are still open.
The Insurance Questions I Hear Most Often
The most common one is about long-term care. After that, the conversation is usually more basic: people do not have coverage, or they do not understand what the coverage is supposed to do.
Is it too late to look at long-term care insurance at 50?
Usually no — but timing matters. Premiums and underwriting get harder as you get older, and waiting into the 60s often means higher cost or fewer options. At 50, many people are still in a workable window. Traditional long-term care insurance, hybrid life/LTC policies, and self-insuring all have trade-offs. We look at the exposure against your assets and family situation first, then talk through the options. Any coverage would be placed through a specialist or, if you want help implementing, through an independent agency.
I don’t really have coverage. Do I actually need it?
That depends on what you are trying to protect. For most high earners, the largest asset is still the ability to earn. Life insurance and disability coverage exist to keep a household and a plan intact if that earning power stops. Umbrella coverage exists because a lawsuit can reach past auto and homeowners limits. The point of a review is to decide which of those risks are worth transferring and which you can reasonably carry.
I have life and disability through work. Is that enough?
Sometimes it is a decent start. It is rarely the whole picture. Group benefits are often based on base salary, may cap the benefit, and can be difficult to keep if you change jobs. The only way to know is to read what the plan actually pays — and what it excludes — then compare that with the income your family would need.
What happens financially if I cannot work?
That is the disability question, and it is the one most people underestimate. A long stretch without earned income is one of the faster ways a plan can get off track. We look at what your group coverage would actually replace, how long it would last, and what would still be uncovered. The details vary by plan, so the review stays specific to your benefits.
I bought policies years ago. I don’t know if they still make sense.
Needs change. Income rises. Kids get older. Estates get more complicated. Some policies still do useful work. Others are oversized, under-sized, owned the wrong way, or sitting with an outdated beneficiary. A periodic review is how you find that out before a claim does.
How does life insurance fit with my estate plan?
Ownership and beneficiaries matter as much as the face amount. A policy owned personally is often included in the taxable estate. In some situations, an irrevocable life insurance trust (ILIT) is used so the death benefit can pass outside the estate. Beneficiary forms also tend to override a will. We look at whether the policy structure matches the rest of the estate plan. Legal documents themselves are handled with your estate attorney.
Do I need an umbrella policy?
Many families with meaningful assets are underinsured on liability without realizing it. An umbrella policy sits on top of auto and homeowners coverage. Whether you need one, and how much, depends on your assets, lifestyle, and current limits. We identify the exposure. Any policy would be placed through an insurance professional.
Does one of these sound familiar?
Schedule a 20-minute call at WolfstoneWeath, call 630-640-3582, or fill out our contact form
How we Approach Insurance Analysis
This is a planning review first. The goal is to understand what you have and what is missing — not to start from a product.
Review what you already own
We look at life, disability, long-term care, umbrella, and the major property/casualty policies in the context of your income, assets, family, and estate plan. The output is a clear picture of what is working, what is redundant, and where the gaps are.
Compare coverage with actual need
Group life and disability benefits are compared with the income and obligations they would need to replace. We stay general on plan terms because they differ. The useful question is whether the benefit would actually hold up your plan.
Look at ownership and beneficiaries
Life insurance is reviewed alongside the estate plan so ownership and beneficiary designations do not quietly undo other documents
Talk through long-term care before the window narrows
We look at the financial exposure first, then the trade-offs among insurance, hybrid policies, and self-insuring. No single approach fits everyone.
Hand off implementation cleanly
After the gaps are clear, placement typically goes to a specialist. If you want help implementing, that can be done through an independent agency. Compensation related to insurance implementation, if any, is disclosed.
Insurance Analysis FAQs
Do you work with clients outside the Chicago suburbs?
Yes. Wolfstone Wealth works with executives and high-income professionals virtually across the country, with in-person meetings available for clients in Naperville, Wheaton, and the greater Chicago area. Most of the work happens by video and secure document sharing, so location is rarely a barrier.
Is 50 too late to consider long-term care coverage?
Usually not, but it is later than the ideal window and earlier than the point where options often shrink. Cost, health, and family history all matter. The first step is understanding the exposure, not picking a policy.
Is employer life and disability coverage enough?
It can be a foundation. For many executives it does not cover total compensation, it may be capped, and it may not travel with you if you leave the company. The plan documents are what tell you what you actually have.
How is this different from talking to an insurance agent?
The starting point is the plan, not a product. We review coverage against your broader financial picture and identify gaps. If something needs to be added or changed, implementation is handled through a specialist or, when you want help placing it, through an independent agency.
How does life insurance interact with an estate plan?
Who owns the policy and who is named as beneficiary often controls where the money goes. Personal ownership can pull the death benefit into the taxable estate. An ILIT is one structure used to change that result. This needs to be coordinated with an estate planning attorney. Ownership and beneficiary coordination is something we cover directly in our Estate Planning work, including ILIT structures.)
What is an umbrella policy?
It is extra liability coverage above your auto and homeowners limits. It is often inexpensive relative to the exposure. Whether it belongs in your plan depends on your assets and current limits.
Still weighing whether this is the right fit?
The first call is always 20 minutes. No commitment, no paperwork. Schedule a call here, or call 630-640-3582 now.
About Christopher Krzus, CFP®
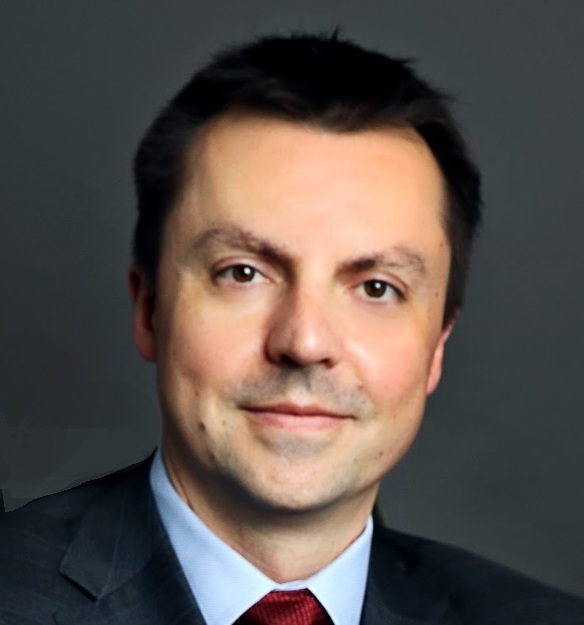
Chris Krzus is the founder and president of Wolfstone Wealth and a fee-only CERTIFIED FINANCIAL PLANNER® with more than two decades of experience. He began his career on the Chicago Board of Trade — an education in markets, risk, and the difference between conviction and noise that informs how he thinks about money to this day. He has since specialized in comprehensive financial planning and investment management for busy and successful tech and business professionals, executives in the accumulation phase, and people navigating major life transitions.
Chris works as a fiduciary, which means he is legally and ethically obligated to act in your interest at all times — not his firm’s, not a product provider’s. He earns no commissions. There are no proprietary products. Just a plan that works for you.
On the tax side specifically, Chris brings integrated thinking to the problems that fall between a tax preparer’s scope and a standard investment advisor’s: RSU and equity compensation planning, Roth conversion strategy, inheritance tax planning for growing estates, and withdrawal sequencing for clients approaching retirement. He coordinates with your existing CPA or tax professional where relevant, so nothing falls through the cracks between the people who are supposed to have it covered.
Not Sure Where to Start?
Most people are not looking to buy more insurance. They want to know if what they have still makes sense — or whether they have been skipping the subject altogether. That is what the first conversation is for
Schedule a 20-minute introductory call →
No paperwork. No obligation. I work with a select number of clients. If it is a fit for both of us, we will know.