
At a certain income level, earning is not the hard part. Deciding where the money should go is.
Retirement, college, taxes, debt, and day-to-day life all pull from the same dollars. Without a clear order, even a strong income can feel like it disappears. We help you map where income should go — and automate as much of that plan as we can — so the important items get funded before the year runs away from you.
By Christopher Krzus, CFP® / Wolfstone Wealth
Why high income doesn’t always feel like you’re getting ahead
Cash flow work for executives and high-income professionals is not expense tracking. It is deciding, in advance, where dollars go: which accounts, which goals, and in what order. Then we put as much of that on rails as we can, especially for bonuses, RSU vests, and other money that shows up in lumps.
I’m a fee-only fiduciary CFP® working with executives and high-income professionals in the Chicago suburbs and virtually across the country. The first conversation is a 20–30 minute Zoom call. No paperwork. No obligation. You get a feel for how I work. I get enough context to know whether I can actually help.
Not sure Where your income is actually going?
The first call is how we both find out if this is a fit. I work with a select number of clients.
The Cash Flow Questions I Hear Most Often
These usually show up in one of two seasons. Earlier in a career, income is rising but the balance sheet is not. Later, college, retirement, and lifestyle are all competing at once. Both are allocation problems. Both get easier when the order is decided before the cash arrives.
I’m making excellent money. Why don’t I feel further ahead?
Income and progress are different things. Income is what hits the account. Progress is what gets kept and pointed at a goal. For a lot of high earners, spending rises in small, reasonable steps — house, schools, travel, the “we can afford it” upgrades — and the savings rate never quite catches up. The issue is rarely a lack of income. It is the absence of a standing plan for where the next dollar goes.
I keep telling myself I’ll save more next year.
Next year is a weak plan. Lifestyle changes made during high-earning years tend to stick. The more useful approach is sequencing: decide what gets funded first, automate that, and spend from what is left. That is not deprivation. It is order.
What is the right order — 401(k), Roth, mortgage, taxable account?
There is no single right order. It depends on your tax bracket, your employer match, whether a backdoor Roth or mega backdoor Roth is available, your timeline, and what else is competing for cash this year. Generic ranking lists miss those details. We map the sequence to your actual income and tax picture, so you are not leaving match money or tax room unused.
College and retirement are hitting at the same time. How do I do both?
This is one of the more common pressure points I see in the mid-40s and 50s. These are not separate decisions. They compete for the same dollars in the same years. We look at both against your income and timeline and build an allocation that does not quietly starve retirement in order to write tuition checks.
How much should I be saving at my income level?
“Save 15%” was not built for someone in a high tax bracket with equity compensation, variable bonuses, and a specific retirement date. The useful number is the one tied to your goals and your time horizon — specific enough to act on, and revisited when compensation or priorities change.
I make a lot of money, but there is never as much left as there should be.”
There is usually a structural reason. It is often a mix of tax drag, account choices that were never revisited, and lifestyle creep that happened one reasonable decision at a time. We look at the whole picture and find the gap between what comes in and what is actually building toward something.
Does one of these sound familiar?
Schedule a 20-30 minute call at WolfstoneWeath, call 630-640-3582, or fill out our contact form. I work with a select number of clients. The first call is how we both decide if this is one of those relationships.
How we Manage Cash Flow
The work is straightforward. We map where dollars will go, then automate what we can. In most cases, that plan is set before the cash comes in.
A standing order for income
We build a clear sequence for paychecks and other regular income: which accounts get funded first, which goals come next, and what is left for lifestyle. Savings does not wait for whatever is leftover at month-end.
A plan for money that arrives in lumps
Bonuses, RSU vests, and option exercises get a pre-set allocation. Tax withholding, savings, and any extra goals are decided ahead of time so those events do not turn into a scramble.
A savings target that matches your situation
We set a savings rate against your income structure, tax picture, timeline, and competing goals — not a generic rule of thumb.
A way to handle competing goals
When college, retirement, debt, and lifestyle are all in the same years, we model the trade-offs so one goal is not funded by quietly abandoning another.
Lifestyle creep, without the lecture
Spending rising with income is normal. The problem is when it rises with no offsetting plan for saving. We look at that pattern in the context of the full plan and put a structure around it so you can live well and still stay on track.
Tied in to the rest of the plan
Where cash goes affects taxes, investment accounts, college funding, and retirement timing. Allocation decisions are made with that full picture in mind, not as a standalone budgeting exercise.
Cash Flow FAQs
How does cash-flow connect to the rest of planning?
Cash flow is what funds everything else; retirement accounts, tax strategy, college, insurance premiums, estate funding. If the allocation is accidental, the rest of the plan is working with leftovers.
How do I handle college and retirement at the same time?
They compete for the same dollars. Retirement generally needs to stay funded because you cannot borrow for it later the way a student can use a mix of savings, aid, work, and loans. We model both together so the allocation reflects your actual priorities and constraints. See this on funding competing milestones for more
Is there a typical order for funding accounts?
A common starting point for many W-2 executives is: capture the full employer 401(k) match, fund an HSA if eligible, work toward maxing the 401(k), consider a backdoor Roth if income is above the direct-contribution limit, then use a taxable account for additional savings. That order changes if your plan allows mega backdoor Roth contributions, if you have a cash-flow crunch this year, or if debt, college, or a business is in the mix. The sequence should follow your situation, not a template
What is lifestyle creep?
It is the gradual rise in spending as income rises, without a matching rise in saving. For high earners it often shows up as a larger house, private school, nicer travel, and a stack of “small” upgrades that each felt reasonable. Together they crowd out the savings rate. The fix is deciding what gets funded first, then spending from what remains.
How much should a high-income professional save?
It depends on income structure, tax bracket, existing assets, retirement date, and what else you are funding. Generic benchmarks miss too much. The useful answer is a number calculated against your actual situation.
Do you work with clients outside the Chicago suburbs?
Yes. Wolfstone Wealth works with executives and high-income professionals virtually across the country, with in-person meetings available for clients in Naperville, Wheaton, and the greater Chicago area. Most of the work happens by video and secure document sharing, so location is rarely a barrier.
Still weighing whether this is the right fit?
The first call is always 20 minutes. No commitment, no paperwork. Schedule a call here, or call 630-640-3582 now.
About Christopher Krzus, CFP®
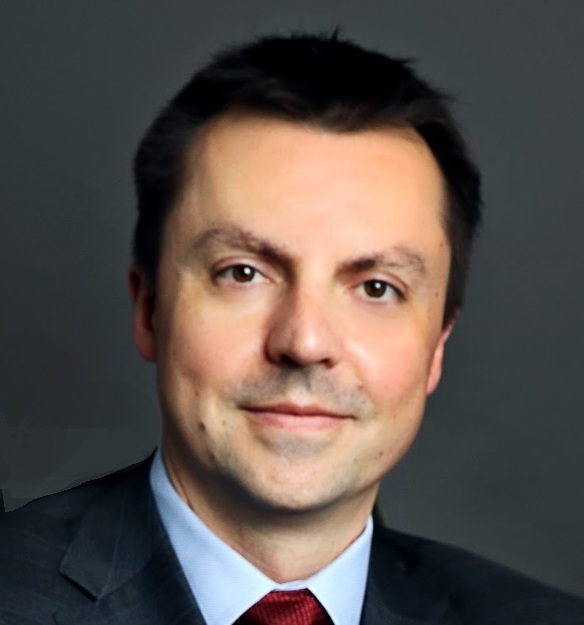
Chris Krzus is the founder and president of Wolfstone Wealth and a fee-only CERTIFIED FINANCIAL PLANNER® with more than two decades of experience. He began his career on the Chicago Board of Trade — an education in markets, risk, and the difference between conviction and noise that informs how he thinks about money to this day. He has since specialized in comprehensive financial planning and investment management for busy and successful tech and business professionals, executives in the accumulation phase, and people navigating major life transitions.
Chris works as a fiduciary, which means he is legally and ethically obligated to act in your interest at all times — not his firm’s, not a product provider’s. He earns no commissions. There are no proprietary products. Just a plan that works for you.
On the tax side specifically, Chris brings integrated thinking to the problems that fall between a tax preparer’s scope and a standard investment advisor’s: RSU and equity compensation planning, Roth conversion strategy, inheritance tax planning for growing estates, and withdrawal sequencing for clients approaching retirement. He coordinates with your existing CPA or tax professional where relevant, so nothing falls through the cracks between the people who are supposed to have it covered.
Not Sure Where to Start?
Most high earners already suspect the money is not landing where it should. The first conversation is for getting a clearer picture — not a pitch.
Schedule a 20-30 minute introductory call →
No paperwork. No obligation. I work with a select number of clients. If it is a fit for both of us, we will know.